
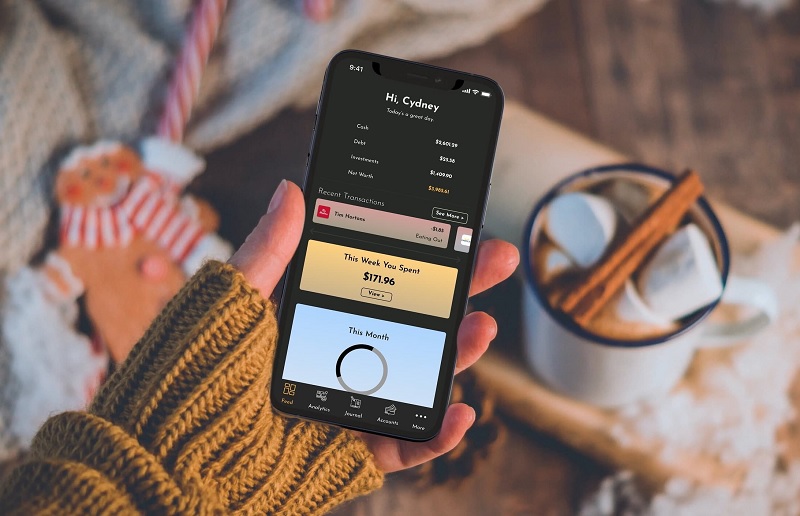
For generations, managing personal finances was an exercise in domestic bookkeeping. It involved keeping heavy paper ledger books on the kitchen table, balancing checkbooks with a handheld calculator, collecting crumpled receipts in shoeboxes, and waiting anxiously for monthly bank statements to arrive in the mail. For many, tracking where every dollar went felt like a tedious administrative chore, leading most people to avoid serious financial oversight until tax season forced their hand. Today, that analog friction has vanished. With a few taps on a smartphone screen, modern consumers can view their complete net worth, monitor real-time spending patterns, track investments, and automate savings goals.
The explosive popularity of personal finance applications represents a massive cultural and technological shift in how everyday people interact with their money. No longer reserved for high-net-worth individuals utilizing dedicated wealth managers, sophisticated financial tools are now universally accessible in the palm of your hand. Understanding why these digital applications have captured the public imagination requires looking at the intersection of modern economic pressures, user-centric technology, and a collective cultural desire for financial empowerment and peace of mind.
The Economic Pressures Driving Digital Adoption
To understand the ubiquity of personal finance apps, one must examine the economic environment in which modern consumers operate. Navigating today’s financial landscape is significantly more complex than it was for previous generations. Economic volatility, rising costs of living, student loan burdens, fluctuating housing markets, and the transition away from traditional employer-funded pensions mean that individuals carry much greater responsibility for their own long-term financial security.
At the same time, our daily transactions have become entirely digitized. Cash has largely been replaced by contactless credit card taps, digital wallet transfers, and subscription-based service models. While this frictionless spending makes daily commerce convenient, it also makes money feel abstract. When you do not physically hand over paper bills, it is remarkably easy to lose track of cumulative spending.
Personal finance applications emerged as a direct antidote to this digital invisibility. By automatically aggregating transactions from multiple credit cards, bank accounts, and investment portfolios into a single dashboard, these apps restore visibility to our financial lives. They act as a real-time mirror, reflecting spending habits and income streams with a clarity that traditional banking statements simply cannot match.
Transforming Financial Literacy Through Automation and Design
One of the primary reasons personal finance apps have achieved such widespread adoption is their radical reinvention of user experience. Traditional financial institutions historically relied on dense jargon, confusing fee structures, and intimidating interfaces that alienated average consumers. Modern fintech developers recognized that financial health is inextricably linked to behavioral psychology.
Instead of treating budgeting as a painful restriction, top-tier financial apps use thoughtful design and behavioral nudges to make money management engaging. Automated categorization algorithms instantly sort your morning coffee, grocery runs, and utility bills into neat visual charts. Instead of manually logging every receipt, users open an app and immediately see a pie chart breaking down their discretionary versus fixed expenses for the month.
Furthermore, automation has democratized proactive saving and investing. Features like round-up savings—where every purchase is rounded up to the nearest dollar and the spare change is automatically funneled into a high-yield savings account—allow users to build financial safety nets effortlessly in the background. By removing the friction of manual transfers and complex decision-making, these tools help users build healthy financial habits almost by accident.
Navigating Security, Privacy, and Trust
Despite their immense popularity, the widespread adoption of personal finance applications did not happen overnight without friction. Entrusting a software application with login credentials for your bank accounts, credit cards, and investment portfolios requires a profound level of consumer trust. Early skeptics worried about data privacy, server vulnerabilities, and the potential security risks of centralizing their entire financial identity within a mobile app.
The fintech industry responded by adopting bank-grade security protocols that match or exceed those used by traditional financial institutions. Modern applications utilize advanced encryption standards, multi-factor authentication, biometric login security, and read-only access models that prevent apps from moving funds directly without explicit user authorization.
Moreover, the rise of secure open banking frameworks allows users to connect their accounts safely through tokenized application programming interfaces rather than sharing raw username and password credentials. As security transparency has improved, consumer comfort has grown exponentially, transforming financial apps from niche tech tools into mainstream household staples.
The Shift From Reactive Budgeting to Proactive Wealth Building
Perhaps the most exciting evolution in the personal finance app ecosystem is the shift in how people use them. Early budgeting tools were primarily reactive; they tracked where your money went after it was already spent, often delivering a sobering verdict at the end of the month.
Today’s applications are increasingly proactive and forward-looking. Advanced platforms incorporate credit score monitoring, net worth tracking, personalized debt-payoff calculators, and goal-based investment planning. Users can simulate different financial scenarios, such as how paying an extra hundred dollars toward a car loan impacts their long-term interest burden, or how delaying retirement contributions by five years affects their nest egg.
This shift empowers everyday individuals to think like strategists. By providing actionable insights, spending anomaly alerts, and tailored financial education directly within the app interface, these tools bridge the knowledge gap that has historically kept people locked out of wealth-building strategies.
Embracing the Digital Financial Ecosystem
The growing popularity of personal finance applications is not a passing technological fad; it is a permanent evolution in how society manages money. By transforming complex economic data into intuitive, actionable, and automated insights, these digital tools have lowered the barrier to financial literacy and given millions of people a stronger sense of control over their economic futures. As technology continues to evolve, the smartphone in your pocket will only become a more powerful partner in helping you build stability, security, and long-term prosperity.